

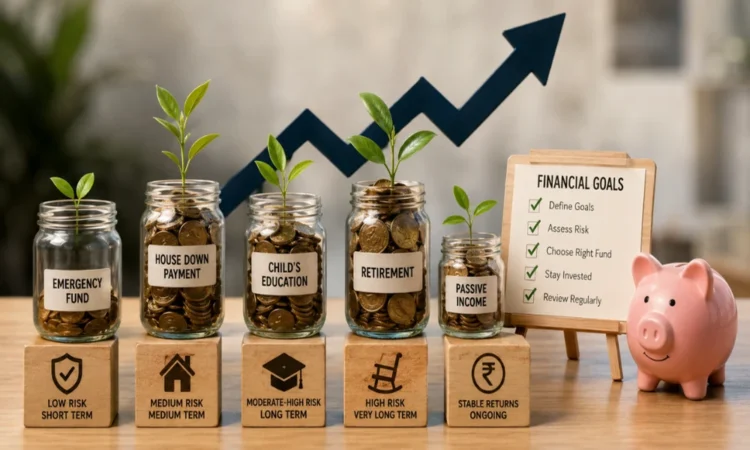

A Mutual Fund can help investors work toward different financial goals by pooling money into a professionally managed portfolio of securities. Depending on the scheme, the portfolio may include equities, debt instruments or a combination of asset classes. This structure can make mutual funds useful for investors who want diversified market exposure without selecting every security individually.
The important part is matching the fund to the goal. An investment intended for retirement several decades away may require a different approach from money being set aside for an expense expected within a few years. Time horizon, risk capacity, liquidity needs and the ability to tolerate market fluctuations should all influence the decision.
Instead of asking whether a particular Mutual Fund is universally good or bad, investors can evaluate whether it is suitable for the specific financial objective they are trying to achieve.
Short Term Goals Need Greater Attention To Stability
Short-term goals generally leave less time to recover from market declines. If an investor needs the money within a relatively short period, large fluctuations can create uncertainty close to the withdrawal date.
For such goals, investors may place greater importance on liquidity and capital stability rather than seeking the highest possible return. The appropriate fund category will depend on the investor’s circumstances and the time remaining before the money is needed.
The key principle is that shorter investment horizons usually allow less room for taking aggressive market risk.
Medium Term Goals Require A Balanced View
Medium-term objectives can include expenses such as education, a planned purchase or another financial requirement several years away.
These goals may offer more flexibility than short-term needs, but the investor still needs to think carefully about volatility. A sharp market decline shortly before the goal date can affect the available amount.
A balanced approach considers both growth potential and the importance of protecting the accumulated corpus as the goal moves closer.
The investment strategy may also need to change gradually rather than remaining identical throughout the entire period.
Long Term Goals Can Allow More Time For Market Cycles
Long-term goals such as retirement may provide investors with more time to remain invested through changing market conditions.
Equity-oriented mutual funds may be considered by investors who have a suitable risk profile and a longer investment horizon because equities can experience significant short-term volatility.
A longer horizon does not guarantee positive returns, but it can provide more time to absorb market fluctuations compared with a near-term goal.
The investment still needs periodic review to ensure that the portfolio remains suitable as the investor’s age, responsibilities and financial position change.
Retirement Planning Needs Consistency More Than Excitement
Retirement investing usually spans many years, making discipline particularly important.
Investors may be tempted to change funds repeatedly based on recent performance or market headlines. Frequent switching can weaken a long-term plan if decisions are driven by short-term emotion rather than meaningful changes in the investment.
A more consistent approach is to define an asset allocation, invest regularly where appropriate and review the portfolio at planned intervals.
As retirement approaches, the level of market risk may also need reassessment because the time available to recover from volatility becomes shorter.
Education Goals Should Account For A Fixed Timeline
Education-related expenses often have a relatively clear time frame. A child may begin higher education in a known number of years, giving the investor an approximate target date.
This makes the investment horizon especially important.
When the goal is still far away, the investor may be able to tolerate greater market fluctuations depending on risk capacity. As the date approaches, protecting accumulated savings may become more important.
The strategy should therefore evolve with the remaining time rather than remaining unchanged until the final year.
Home Purchase Goals Need Liquidity Planning
Saving for a house deposit or other property-related expense can involve a large financial target.
Investors should estimate both the target amount and the likely time when the money will be required. A fund that carries substantial market risk may not be suitable if the purchase is expected soon.
Liquidity also matters because property transactions can require funds at specific stages.
Planning the investment around the expected payment schedule can reduce the risk of being forced to redeem during an unfavourable market period.
Emergency Money Should Usually Remain Separate
Mutual funds can play a role in broader financial planning, but long-term investments should not necessarily become the first source of money during every emergency.
Keeping a separate emergency reserve can reduce pressure to redeem market-linked investments unexpectedly.
If investors repeatedly withdraw from long-term goals to cover routine financial shortfalls, the original plan may struggle to stay on track.
A separate emergency fund can provide flexibility while allowing goal-based investments to remain invested according to their intended horizon.
Digital Access Can Make Goal Tracking Easier
A Mutual Fund App can help investors review holdings, track supported investment information and manage parts of their mutual fund activity digitally.
The convenience can be useful when several goals are being managed at the same time. Investors may find it easier to see whether contributions are continuing and whether the overall portfolio remains aligned with the original plan.
Digital visibility should not lead to excessive monitoring, however. Long-term goals generally do not need decisions based on every daily market movement.
The app is most useful when it supports discipline rather than encouraging frequent changes.
One Fund Should Not Be Expected To Serve Every Goal
A single mutual fund may not be suitable for all financial objectives.
Different goals can have different timelines, risk levels and liquidity requirements. Using the same aggressive strategy for retirement and a near-term education expense can expose the shorter goal to unnecessary volatility.
Investors should therefore consider the purpose of each allocation separately.
This can also make portfolio reviews more meaningful because the performance of each investment can be judged against the goal it was selected to support.
Asset Allocation Can Connect Goals With Risk
Asset allocation refers to how money is divided across different asset classes.
An investor with a long time horizon and higher risk capacity may hold a larger proportion in growth-oriented assets, while another investor with a shorter horizon may prefer a more conservative mix.
The appropriate allocation depends on personal circumstances rather than a universal formula.
Over time, market movements can change the original allocation. Periodic rebalancing may help bring the portfolio back closer to the intended level of risk.
Regular Contributions Can Support Goal Discipline
Investing a fixed amount at regular intervals can make goal-based planning more systematic.
Instead of waiting for a perfect market entry point, investors may continue contributing according to their financial plan. This can also help connect monthly savings with long-term objectives.
Regular investing does not guarantee profits or prevent losses. Its main benefit is consistency.
The contribution amount should still be realistic and should not interfere with essential expenses or emergency savings.
Avoid Chasing The Fund With The Highest Recent Return
Performance rankings can change quickly.
A fund that appears near the top of a category during one period may not remain there in the future. Selecting investments only from recent return tables can lead investors to enter after a strong period without understanding the underlying strategy.
A better assessment considers the fund’s category, objective, portfolio approach, risk level and costs.
Past performance can provide context, but it should not be treated as a promise of future results.
Costs Matter More Over Longer Goals
Mutual funds involve expenses that can influence long-term outcomes.
The applicable expense ratio and other permitted costs reduce the amount that remains invested over time. Even relatively small differences can become more noticeable when investments continue for many years.
This does not mean investors should automatically select the cheapest fund available. Suitability and investment strategy still matter.
Costs should simply be included alongside risk, objective and consistency when comparing options.
Goal Reviews Should Include Life Changes
A financial goal does not exist separately from the investor’s life.
Income changes, marriage, children, career transitions or new financial responsibilities can all affect the amount available for investing and the level of risk the investor can reasonably take.
Periodic reviews should therefore look at both the investment and the investor’s circumstances.
Sometimes the fund may remain suitable while the contribution amount needs adjustment. In other cases, the time horizon or risk profile may have changed enough to justify a broader portfolio review.
Reduce Risk As The Goal Gets Closer
One common planning issue is maintaining the same level of market exposure right until the money is needed.
If a long-term goal has accumulated a substantial corpus and the withdrawal date is approaching, a sharp market decline can create a larger impact than it would have years earlier.
Investors may therefore consider gradually reducing exposure to higher-volatility assets as the goal approaches, depending on their strategy and circumstances.
The purpose is not to predict a market fall. It is to reduce the chance that short-term volatility disrupts a goal that is close to being funded.
Conclusion
A Mutual Fund can support a range of financial goals when the investment is selected according to time horizon, risk capacity and liquidity needs. Short-term, medium-term and long-term objectives should not automatically use the same strategy because the consequences of market volatility differ across each time frame.
Goal-based investing becomes stronger when investors maintain emergency savings, review asset allocation, account for costs and adjust risk as important dates approach. Regular contributions can support discipline, but the portfolio should still be reviewed when financial circumstances change.
Anyone using mutual funds to participate in the broader Stock Market should remember that professional management and diversification can help organise investments, but market-linked returns remain uncertain and losses are possible.
FAQs
1. Can A Mutual Fund Be Used For Long Term Goals?
Yes, suitable mutual funds may support long-term goals when the fund’s risk profile matches the investor’s horizon and financial plan.
2. Should The Same Mutual Fund Be Used For Every Goal?
No, different goals may require different levels of risk, liquidity and investment duration.
3. Does A Mutual Fund Guarantee Goal Achievement?
No, mutual fund returns are market-linked and cannot guarantee that a specific financial target will be reached.
4. Should Risk Be Reduced As A Goal Gets Closer?
It may be appropriate to reassess and reduce portfolio volatility as an important financial goal approaches.
5. Is Regular Investing Useful For Goal Planning?
Yes, regular contributions can support investment discipline, although they do not guarantee returns or eliminate market risk.